Buying guide: Stamp duty
Can You Add Stamp Duty to Your Mortgage? (UK 2026)
Last updated:
Type the full address with its postcode to go straight to your report options. Try .
- 65+ official sources
- Emailed within 24 hours, usually faster
- Sources and coverage gaps named
- One-off payment, no subscription
What the report looks like inside
See the full sample →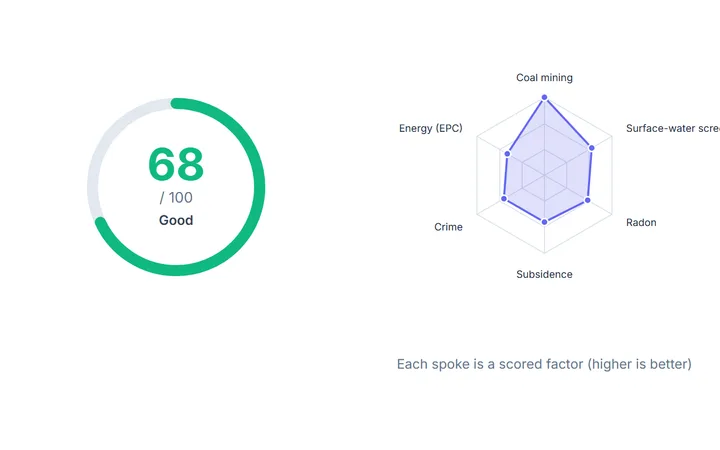 IQ Score and the factors behind it
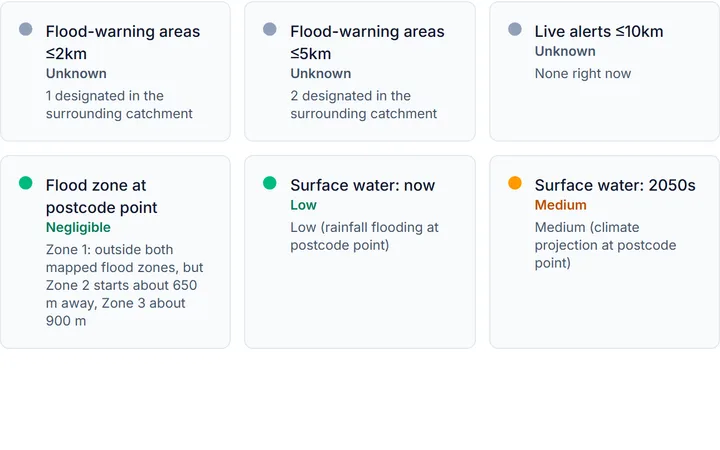 Flood risk at the postcode point
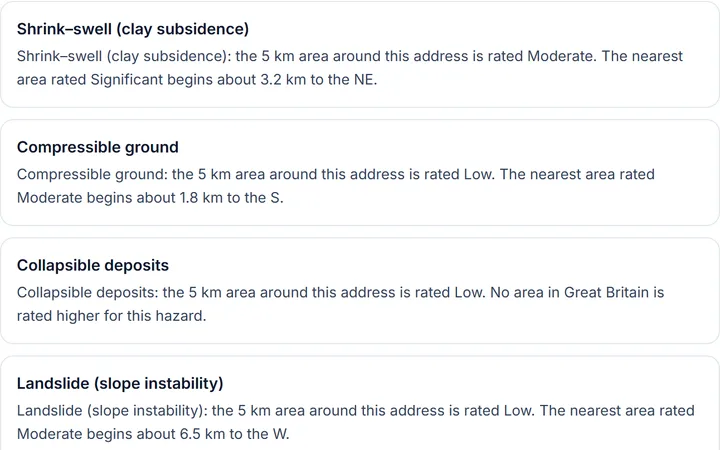 Six ground hazards, rated for the area
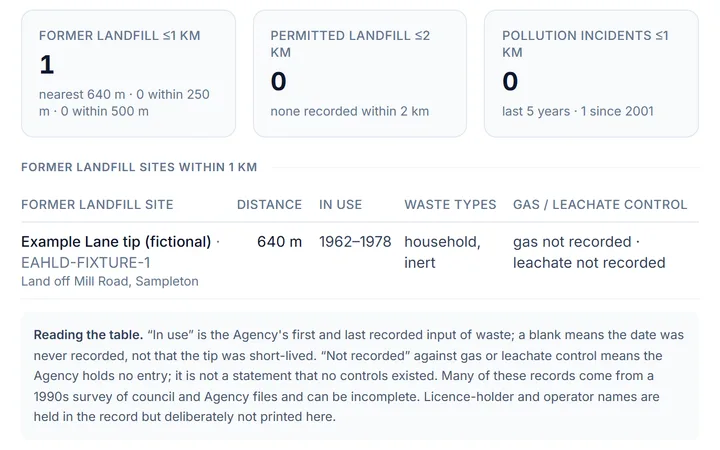 Landfill, permits and incidents nearby
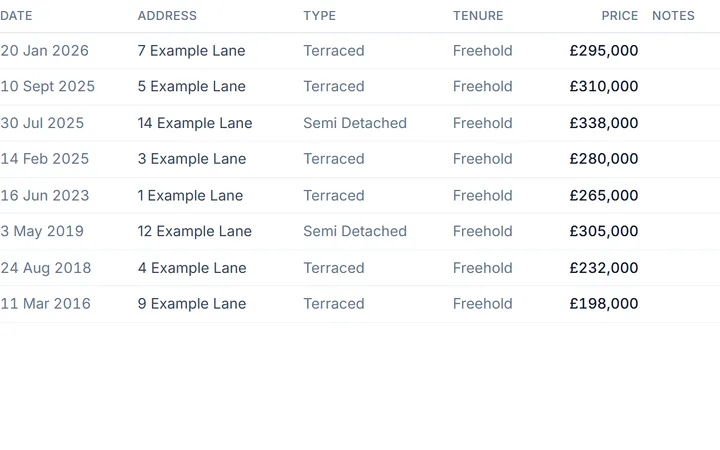 What homes here sold for
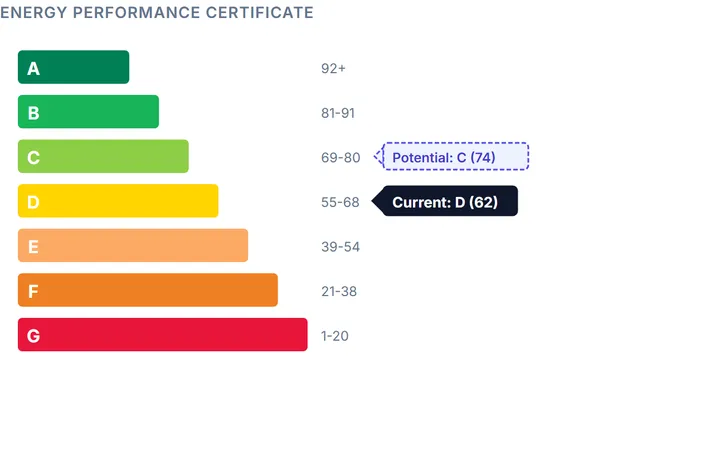 The energy rating, now and after upgrades
Illustrative sample · fictional address · cut from the sample report as it prints
Quick answer
Indirectly, yes, but not in the way most people mean. You can't pay Stamp Duty (SDLT) out of your mortgage directly: it's due to HMRC within 14 days of completion and your solicitor pays it from your own funds. What you can sometimes do is borrow a larger mortgage (a lower deposit) and use the freed-up cash to cover the SDLT. That only works if the higher loan keeps you within the lender's loan-to-value and affordability limits, and it means paying interest on that amount for the mortgage term.
How 'adding stamp duty to your mortgage' actually works
Stamp duty is a cash cost at completion. To spread it, buyers reduce their deposit and borrow more, keeping back the difference to pay the SDLT. For example, instead of putting your full savings into the deposit, you keep enough aside for the tax and increase the loan slightly. The lender never pays HMRC for you: your conveyancer does, from your account, within the 14-day deadline.
What does it cost you to borrow the stamp duty?
Rolling SDLT into the loan increases both your monthly payment and the total interest you pay over the term. A few thousand pounds of tax added to a 25- or 30-year mortgage can cost noticeably more than its face value once interest is included, and a higher loan-to-value can push you into a more expensive rate band. Work out the SDLT first with our Stamp Duty Calculator, then decide whether borrowing it is worth the long-run cost.
When can't you add stamp duty to your mortgage?
You can't if the bigger loan breaches the lender's maximum loan-to-value (often 90–95%) or fails their affordability assessment. First-time buyers on tight deposits are most likely to hit these limits. If you qualify for first-time buyer relief you may owe little or no SDLT anyway. Check with our First-Time Buyer Stamp Duty Calculator.
Know the full cost of the property before you stretch the loan
Before you borrow more to cover stamp duty, make sure the property is worth it. HouseCheckup runs 15+ checks on the exact address from official sources (flood risk, planning, EPC, lease and more), so a stretched budget goes into a home that stacks up. £24.99 (Complete), one-off.
Type the full address with its postcode to go straight to your report options. Try .
£24.99 one-off · no subscription · hand-checked by a person and emailed within 24 hours, usually faster.
Cancel for a full refund at any time before your report is emailed. Terms
Sources
- Stamp Duty Land Tax: payment and deadlines, GOV.UK / HMRC
- How much deposit and borrowing: loan-to-value basics, MoneyHelper
How HouseCheckup works
From search to full report in three simple steps.
- England, Wales & Scotland
Search any address
Enter an address in England, Wales and Scotland. Coverage varies by nation and source.
- Before you pay
See the IQ Score
See an initial area risk screen where enough data is available, with the checks and coverage behind the score.
- Emailed within 24 hours
Get the full report
Choose Lite (£9.99) or Complete (£24.99). The report is emailed to you within 24 hours, usually faster, with every source named and any check it could not run stated.
Frequently asked questions
Can you add stamp duty to your mortgage?
Is it a good idea to add stamp duty to your mortgage?
When do you have to pay stamp duty?
Can first-time buyers avoid paying stamp duty?
Still have a question? We typically respond within 24 hours.
Ready to check a property?
Enter the address you are thinking of buying. See the available area risk data, then choose an emailed report for the property.
Type the full address with its postcode to go straight to your report options. Try .
Reports from £9.99, one-off. Compare Lite and Complete
Cancel for a full refund at any time before your report is emailed. Terms
At a glance
One-off
No subscription
Pay once for each report you buy.
Named
Sources & coverage
Every report names its sources and the checks it could not run.
GB
England, Wales & Scotland
Coverage varies by nation and source, and is stated.
£9.99
Reports from
Lite £9.99, Complete £24.99.