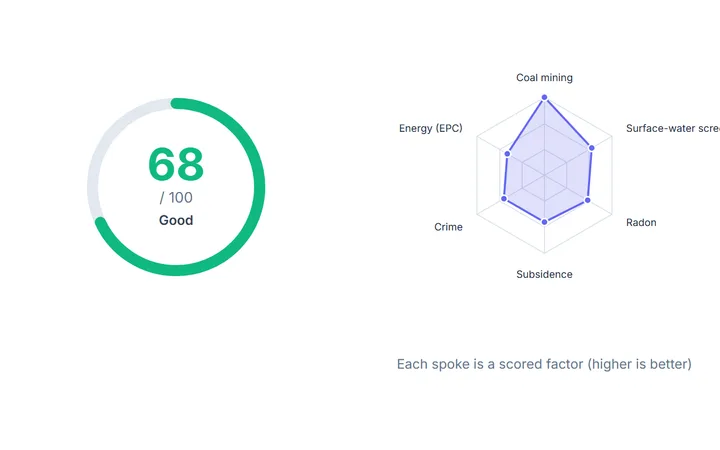
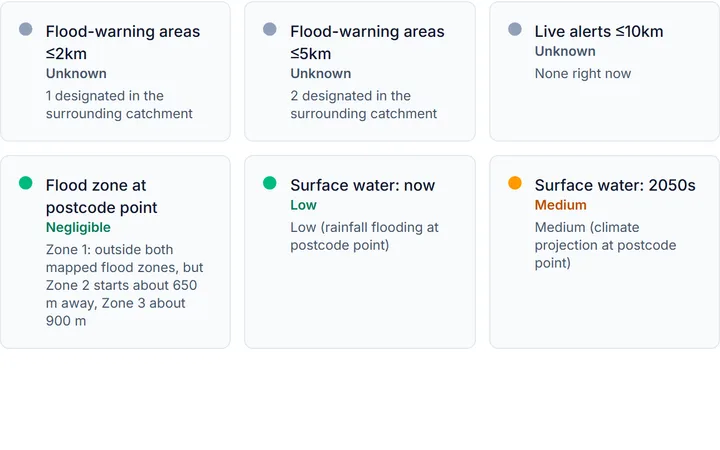
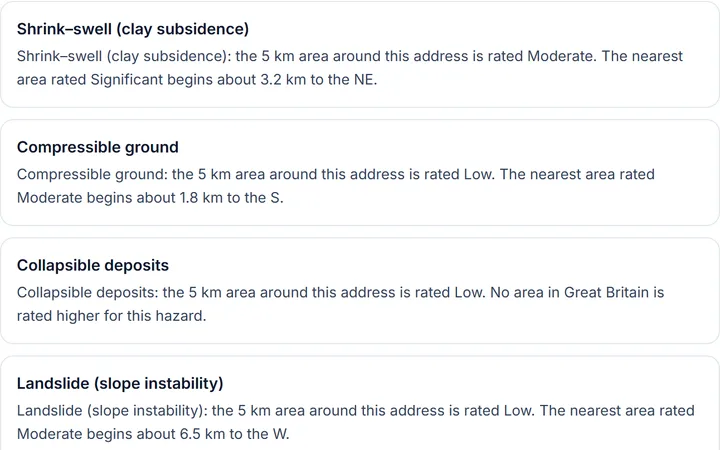
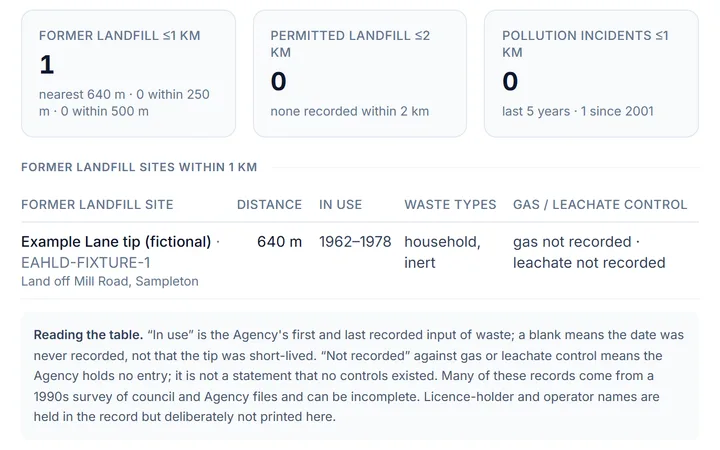
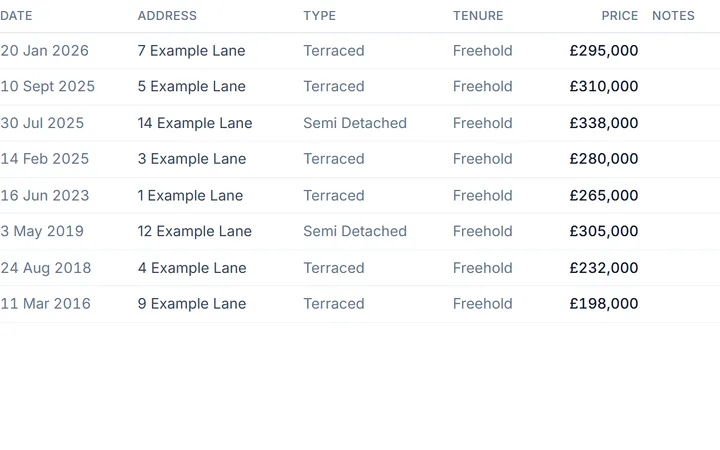
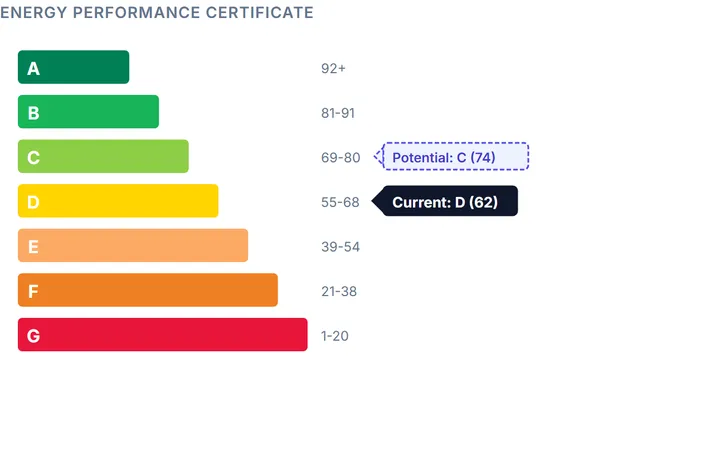
There are over 200,000 shared ownership households in England according to the English Housing Survey, and the scheme enables thousands of first-time buyers annually to purchase homes they couldn't otherwise afford. At HouseCheckup, our £24.99 property reports provide essential data for shared ownership buyers (including EPC ratings, flood risk, local comparables, and planning history), because buying a share of a property still requires the same due diligence as buying 100%. This guide explains exactly how shared ownership works, what it costs, and whether it's right for you.
What Is Shared Ownership?
Shared ownership is a government-backed scheme that allows you to buy a share of a property (between 25% and 75%) and pay rent on the remaining share to a housing association. You need a mortgage and deposit for only your share, making the upfront costs significantly lower than buying outright.
Example: A property worth £300,000 with a 25% share:
- Your share: £75,000
- Your deposit (10% of your share): £7,500
- Your mortgage: £67,500
- Monthly rent on the 75% you don't own: approximately £562 (at 2.75% of £225,000 / 12)
Compared to buying outright at £300,000 where you'd need a £30,000 deposit and £270,000 mortgage, shared ownership dramatically reduces the entry barrier.
The New Model (Post-April 2021)
The government updated the shared ownership model from April 2021. Key changes include:
- Lower initial share: You can now buy from 10% (previously 25% minimum) in some developments
- Gradual staircasing: Buy additional 1% shares per year for the first 15 years (previously minimum 10% staircasing)
- 10-year repairs responsibility: The housing association covers the cost of essential repairs for the first 10 years (on new-build properties sold under the new model)
- Improved lease terms: New leases must meet the new model requirements, offering better protections for buyers
Important: Not all shared ownership properties use the new model. Resales of older shared ownership properties operate under the original terms. Always check which model applies.
Who Is Eligible?
Shared ownership is aimed at people who can't afford to buy outright. You must:
- Have a household income of £80,000 or less (£90,000 or less in London)
- Be a first-time buyer, or a previous homeowner who can't afford to buy now, or an existing shared owner looking to move
- Not own another property at the time of purchase (you must sell any existing property)
- Be unable to buy a suitable home without assistance (the housing association assesses this)
- Meet the housing association's financial assessment requirements (affordability check)
Military personnel have additional priority through the Forces Help to Buy scheme in conjunction with shared ownership.
The Costs: What You Actually Pay Monthly
Shared ownership monthly costs typically include:
Mortgage Payment
Based on your share only. For a £67,500 mortgage at 5% over 25 years: approximately £395/month.
Rent
Typically 2.75% of the unsold share per year, paid monthly. For a £225,000 unsold share: approximately £516/month. Rent increases annually, usually by RPI + 0.5% (or CPI + 1% for newer properties).
Service Charges
You pay 100% of service charges regardless of your ownership share. These cover maintenance of communal areas, buildings insurance, and management fees. For flats, expect £100-£300+/month. For houses, usually less.
Total Monthly Cost (Example)
| Cost | Monthly Amount |
|---|---|
| Mortgage (£67,500 at 5%, 25 years) | £395 |
| Rent (2.75% of £225,000) | £516 |
| Service charge (flat) | £200 |
| Total | £1,111 |
Compare this to renting a similar £300,000 property privately (perhaps £1,200-£1,500/month) or buying outright (£1,579/month mortgage on £270,000 at 5%). Shared ownership is cheaper monthly, but you're building equity on only your share.
Staircasing: Buying More Shares
Staircasing means buying additional shares in your property over time. When you staircase:
- The property is revalued at current market value
- You buy additional shares at the current value (which may be higher or lower than when you first bought)
- Your rent reduces proportionally
- At 100% ownership, you become a full owner and pay no rent
Staircasing Costs
Each staircasing transaction involves costs:
- Valuation fee: £200-£500
- Legal fees: £500-£1,000
- Mortgage arrangement fees: If remortgaging to fund the additional share
- Stamp duty: Payable on staircasing transactions above SDLT thresholds
Under the new model, 1% per year staircasing for the first 15 years has lower legal costs, making gradual staircasing more practical.
Selling a Shared Ownership Property
Selling shared ownership works differently from selling a standard property:
Nomination Period
The housing association typically has the right to find a buyer for your property first (nomination period, usually 4-8 weeks). They'll market it to eligible shared ownership buyers.
If They Can't Find a Buyer
After the nomination period, you can sell on the open market. If you own less than 100%, the buyer must be eligible for shared ownership. If you've staircased to 100%, you can sell to anyone.
Resale Challenges
Shared ownership properties can be harder to sell because:
- The buyer pool is limited to eligible applicants (unless you own 100%)
- Not all lenders offer shared ownership mortgages, reducing buyer options
- The housing association's involvement adds complexity
- Some buyers are put off by the rent + mortgage + service charge structure
Pros of Shared Ownership
- Get on the ladder: Buy with a much smaller deposit than outright purchase
- Lower monthly costs: Typically cheaper than renting privately or buying outright
- Build equity: Your share gains value as property prices rise
- Staircase to full ownership: Eventually own 100% and pay no rent
- New-build quality: Many shared ownership properties are new-builds with warranties
- Government backing: The scheme has political support across parties
- 10-year repair cover: New model properties have housing association repair responsibility for the first decade
Cons of Shared Ownership
- You don't fully own your home: You're part-owner, part-tenant, with obligations to the housing association
- Rent increases: Rent on the unsold share increases annually (typically CPI + 1%), potentially outpacing wage growth
- Service charges: You pay 100% of service charges despite owning only a share
- Staircasing costs: Each staircasing transaction involves fees, and the property may have increased in value (making additional shares more expensive)
- Restrictions on alterations: You typically need housing association permission for modifications
- Harder to sell: Nomination periods, eligible buyer requirements, and limited lender options
- Leasehold: Most shared ownership is leasehold, with associated lease length and management issues
- Negative equity risk: If the property value falls, you still owe rent on the unsold share at its original valuation
Shared Ownership vs Alternatives
| Option | Deposit Needed (£300K property) | Monthly Cost | Equity Building |
|---|---|---|---|
| Shared ownership (25%) | £7,500 | £1,111 | 25% of growth |
| Help to Buy (closed) | £15,000 | £1,350 | 80% of growth |
| 95% mortgage | £15,000 | £1,680 | 100% of growth |
| Private renting | £2,400 (deposit) | £1,300 | None |
Things to Check Before Buying
- Lease length: Should be 990 years for new-build shared ownership. Shorter leases (below 80 years) create problems
- Service charge history: Request 3 years of accounts. Check for upcoming major works
- Rent review mechanism: Understand exactly how rent increases are calculated
- Staircasing restrictions: Check whether there are any restrictions on when or how much you can staircase
- Housing association track record: Research the housing association's reputation for maintenance and management
- Resale history: How quickly do shared ownership resales in this development sell?
Research Your Shared Ownership Property
A HouseCheckup report for £24.99 (Complete tier) gives shared ownership buyers the same comprehensive data as any other purchaser: flood risk, subsidence risk, EPC ratings, planning history, and local market data. Buying a 25% share of a property with hidden problems is just as costly as buying 100% of one. Make sure the property you're investing in is sound, whatever your share size. At £24.99, it's an essential step before committing to any shared ownership purchase.
Buying in this area? Check the exact property.
Complete (£24.99) brings available property records into a human-checked report. Flood and ground screening, crime, energy and sale-record context have different source and location limits. Postcode and regional data cannot establish the condition of a building; unanswered checks remain explicit.
Type the full address with its postcode to go straight to your report options. Try .
£24.99 one-off · no subscription · Human-checked and emailed to you. See a sample report · Review report options and coverage
Cancel for a full refund at any time before your report is emailed. Terms
Last updated: