Buying guide: Should I buy a house with…
Should I Buy a House With a History of Subsidence?
Last updated:
Type the full address with its postcode to go straight to your report options. Try .
- 65+ official sources
- Emailed within 24 hours, usually faster
- Sources and coverage gaps named
- One-off payment, no subscription
What the report looks like inside
See the full sample →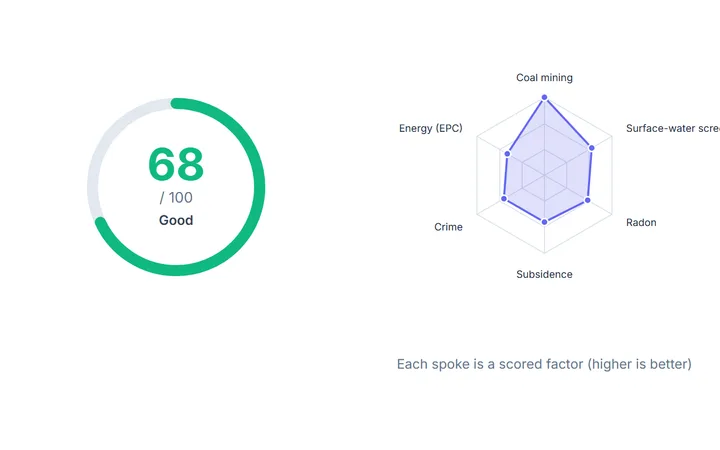 IQ Score and the factors behind it
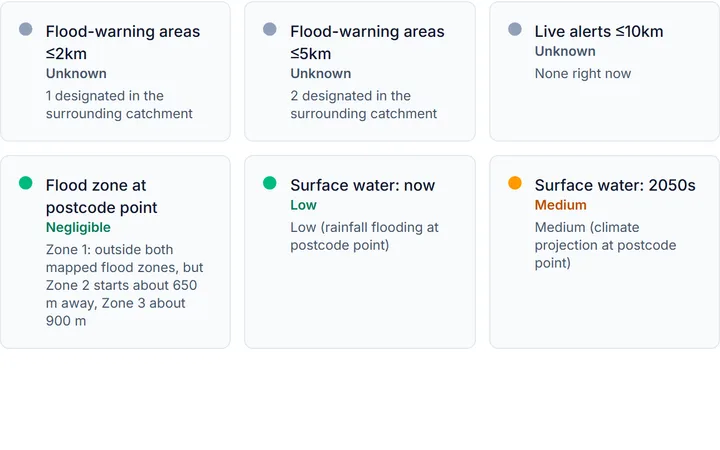 Flood risk at the postcode point
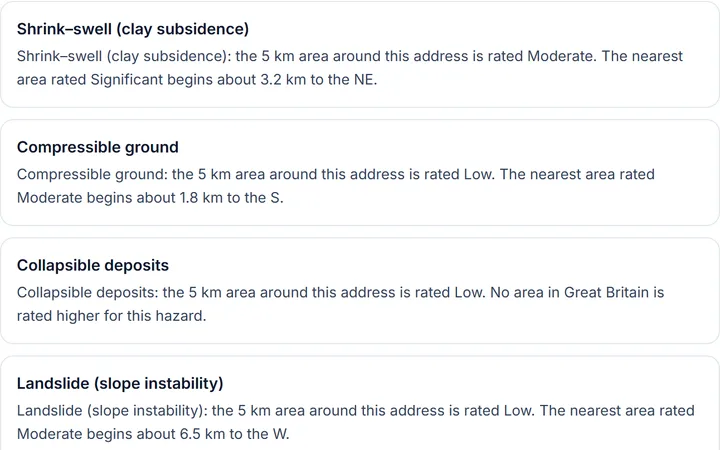 Six ground hazards, rated for the area
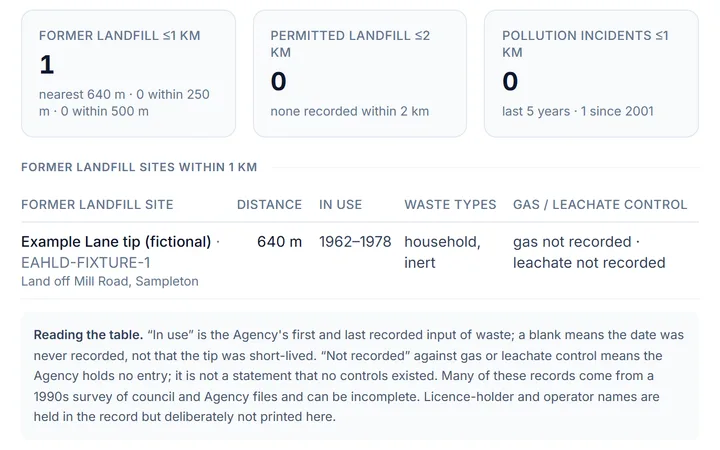 Landfill, permits and incidents nearby
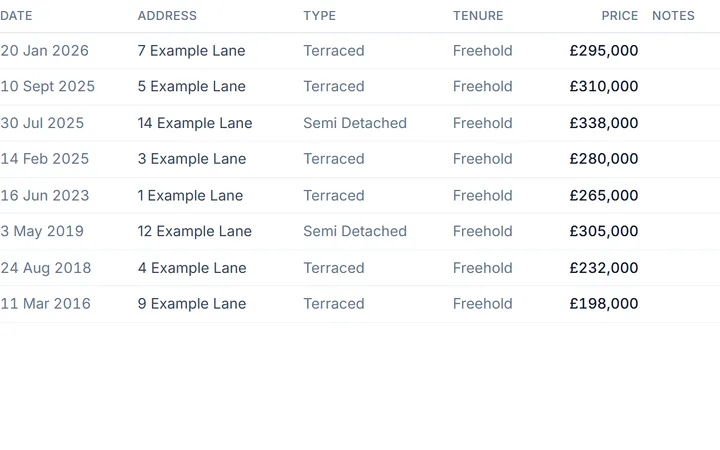 What homes here sold for
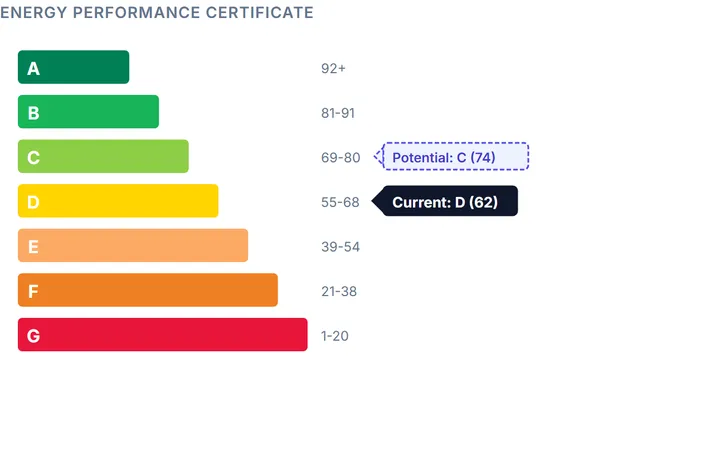 The energy rating, now and after upgrades
Illustrative sample · fictional address · cut from the sample report as it prints
The short answer
You can buy a house with a subsidence history if it has been properly repaired, has a clean post-works monitoring record and remains insurable, ideally with the existing insurer willing to continue cover. Past subsidence is not automatically disqualifying, but unresolved or repeatedly recurring movement, or a property you cannot insure, is a serious red flag.
The real risk
Subsidence is downward ground movement that causes a building to crack and distort, most often from shrinkable clay soils drying out, nearby trees, leaking drains or former mining. Once a property has had a claim, insurance can become harder and more expensive, and you may be tied to the existing insurer.
The critical question is not 'did it move?' but 'was it fixed and has it stayed still?'. A property underpinned years ago with a clean monitoring record and a structural-engineer sign-off can be a sound, well-priced buy. Active or recurring movement is a different matter.
A subsidence history must be disclosed by the seller, and a buildings survey (RICS Level 2 or 3) is strongly advised to assess the current condition.
What the data reveals
British Geological Survey GeoSure
Shows shrink-swell clay and other ground-stability hazards for the area, the underlying cause of most non-mining subsidence.
Environmental/ground-stability search
Flags collapsible ground, made ground and mining alongside natural shrink-swell risk.
Seller disclosure + insurance history
Past claims, underpinning records and the existing insurer's willingness to continue cover are decisive.
RICS building survey
Assesses current cracking, movement and whether past repairs are holding.
How to check this exact address
- 1Check the property's ground-stability flags (shrink-swell, mining) in a HouseCheckup report before you offer.
- 2Commission a RICS Level 2 or Level 3 survey to assess current structural condition.
- 3Ask the seller for underpinning records, structural-engineer reports and the claims history.
- 4Confirm you can obtain (and ideally continue) buildings insurance on the address.
Worried about subsidence history at a specific address?
General guidance only gets you so far. The answer that matters is about the one house you're considering. HouseCheckup pulls flood risk, ground stability, mining, planning, EPC, crime and sold-price history (15+ checks from official sources) into a single buyer-grade report on that exact address, so you can triage it before committing to the £250–450 conveyancing search pack.
Type the full address with its postcode to go straight to your report options. Try .
£24.99 one-off · no subscription · hand-checked by a person and emailed within 24 hours, usually faster. See a sample report
Cancel for a full refund at any time before your report is emailed. Terms
Check this postcode's ground risk
Before you rely on a seller's disclosure, screen the area yourself. Our free ground-stability checker shows the BGS clay shrink-swell class, coalfield status and recorded landslides for any postcode, then check the exact address before you offer.
Sources
- BGS GeoSure: ground stability data, British Geological Survey
- RICS Home Surveys consumer guide, RICS
How HouseCheckup works
From search to full report in three simple steps.
- England, Wales & Scotland
Search any address
Enter an address in England, Wales and Scotland. Coverage varies by nation and source.
- Before you pay
See the IQ Score
See an initial area risk screen where enough data is available, with the checks and coverage behind the score.
- Emailed within 24 hours
Get the full report
Choose Lite (£9.99) or Complete (£24.99). The report is emailed to you within 24 hours, usually faster, with every source named and any check it could not run stated.
Frequently asked questions
Is a house with past subsidence a bad buy?
Can you insure a house that has had subsidence?
Does subsidence have to be disclosed when selling?
Still have a question? We typically respond within 24 hours.
Ready to check a property?
Enter the address you are thinking of buying. See the available area risk data, then choose an emailed report for the property.
Type the full address with its postcode to go straight to your report options. Try .
Reports from £9.99, one-off. Compare Lite and Complete
Cancel for a full refund at any time before your report is emailed. Terms
At a glance
One-off
No subscription
Pay once for each report you buy.
Named
Sources & coverage
Every report names its sources and the checks it could not run.
GB
England, Wales & Scotland
Coverage varies by nation and source, and is stated.
£9.99
Reports from
Lite £9.99, Complete £24.99.